Over dinner in a trendy late nineties New York Vietnamese, a friend closely associated with the early development of the Tommy Bahama men’s apparel brand excitedly told me how Nordstrom had agreed that week to stock the brand. Part joy and part fear hung in the air that night about delivering upon the promises her team had made. A finance guy had run into her office, as she left her office and asked what numbers he could put against this prospect in the next three years cashflow forecast? She could tell him what stock was being shipped to the nationwide department store but the sales figures were simply guess work with a high level of variance (risk). She defaulted to some generic figures her Nordstrom buyer had suggested. No one knew, nor was the real business transparent until the customers came into the store (this pre-dated Nordstrom’s online sales platform).
I make this observation because as exciting as it is to have a huge corporation with big “reach” offer to collaborate with a new product or service line, there is no business until the cash register rings.
The simple act of consistently “showing up” (in-person, virtually or by phone or email) is a long overlooked super-power in business. Would others describe that as one of your super-powers, if not why not?
The number of clients and prospects I meet, who lack the routine and exceptional discipline particularly in periods of a business transition: raising capital, a business acquisition, or on-boarding a new team, and use it as an excuse not to lock in a meeting date, get on a plane or return a call or email in a timely manner to a prospective new business partner or client is staggering.
They then convince themselves it is a secondary or tertiary priority when the reality is building their business, and ensuring there is sufficient fuel in the tank, is a constant priority if they are serious. It is not “either or”, it is “both”. It begs the rhetorical question why should they make you their future priority (bring you business)?
The concept of “reverse benchmarking” is greatly overlooked by a lot of entrepreneurs, executives and investors. When everyone turns up to a business meeting in a suit with an open neck white shirt, they look like extras in a film. A sea of dullness, and a lack of originality.
Rather than fret about what the competition are doing better than you, why not focus on what you excel at that they don’t, and do it consistently better than they ever do. People will remember and remark on that if they recall nothing further from their interaction.
I have only had two clients in 35 years of business, who have threatened to or failed to pay me for my advice. Most trusted advisers will rarely tell you their war stories (personal embarrassment or vulnerability). I am a contrarian. We learn from our own and others’ misfortune and build an “institutional warning system” and risk mitigation with experience.
Situation No.1: The first a Dubai royal family-backed hotel luxury management company, Tiara Hotels and Resorts, fired my buyer and the entire executive management team in the midst of the 2008 financial crisis. The remaining employee a UAE Financial Controller sought to renege on our agreement, and outstanding invoices.
My response: a robust chronological provision of all correspondence and a face-to-face meeting in his office, which led to acceptance that all project objectives have been realistically met led to release of the £60,000 equivalent monies owed.
Lesson Learned: doing business in seemingly cash-rich, hard charging and “first world” economies, backed by sovereign wealth, and led by world-renown executives, is not “risk-free”. Where local legal systems are tilted in favour of local businesses, the best form of protection in corporate advisory is (1) demanding 100% payment upfront or front-loaded increments that exceed the value delivered, (2) be highly judicious about where and with whom you do business, and (3) high growth markets are invariably more fragile than you ever imagine and you need to be factoring in a “risk premium” as an advisor.
Situation No.2: A mid 50s seasoned Florida tech entrepreneur with two successful exits was introduced to me by a childhood friend of his and business acquaintance, seeking counsel about the profitable growth and expansion of his latest venture. His appearance, convivial demeanor, and the setting over Zoom in the midst of Covid reflected his past success, and enviable country club lifestyle. Against my first principles of “no upfront payment, no advice”, we agreed a 6-month retainer with two staged payments from his personal holding company, not the new venture, at 3 months, and 6 months. Fees due, as invoiced. Our weekly calls would touch on his progress attracting capital, product approvals/feedback, and developments within his team and strategy. As the months went by, he asked in good faith for the first payment ($18,000) to be aggregated with the second on the understanding our relationship would extend substantially beyond 6 months. With growing trust in our weekly engagement, I agreed against my better judgement. As could be foreseen, his capital raise and regulatory approvals overran our immediate 6-month advisory term. Conversations about an extension were met with stalling emails. Invoices went unpaid for 1, 3, 6, 12 months and beyond. Text and email apologies and guarantees of payment then hit a wall of silence. I was being “ghosted”.
My response: Offers to mediate our growing dispute by voicemail, email and text and through the intervention of our referral source, merely led to “acknowledgement of the debt and I’ll honour it!”. Yet his actions conveyed the polar opposite. As the quarters clicked past, I’d send reminders including fresh invoices with the compounding interest he had proposed at the outset of our engagement for deferment to a mid-term payment. I weighed up legal action or debt recovery services to recoup the $40,000 debt but the probable time and expense outweighed investing good money after bad money. I was soon to learn that I was not alone when major US lenders pushed a foreclosure action on his home, and to cap it off, he pulled the same deceit several years later on his childhood friend.
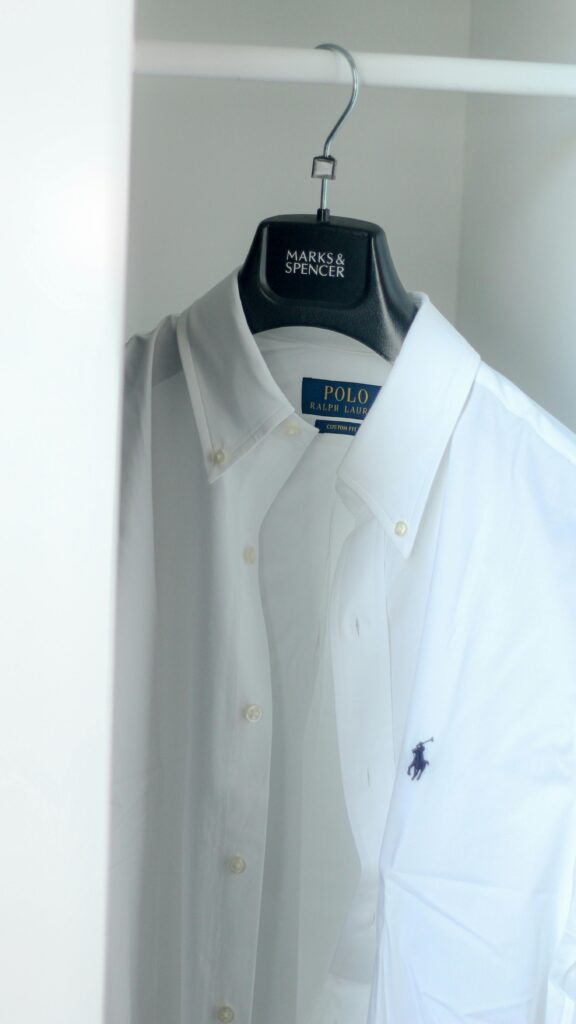
Lesson Learned: in the world of trusted advisory world don’t confuse the reassurance a trusted referral source might give you, a well-to-do client’s accouterments of wealth or a prospect’s past success with an upfront financial commitment before you start working together. Fraudulent and unethical clients come in all clothing, sex and sizes, including sitting behind mahogany desks, wearing crisp white Ralph Lauren shirts, and gently lifting their horn-rimmed Dior spectacles to tell you about their kids exploits in the weekend’s country club tennis tournament. None of us can predict the future but we can expand our control over the entrepreneurial risks that we are taking today.
Life isn’t fair, and nor is business as solo or small boutique advisory business owner. Get wise and stick to your principles!
Is your positioning to your ideal commercial partners, ideal client buyers and ideal investors largely a re-stating verbatim of your methodology (features or benefits) or prefaced, in powerful language that demonstrably portrays your “fame”, driven by the scarcity and dramatic value that you are putting on the table now, giving you maximum control of the immediate discussion?
A great many highly seasoned entrepreneurs, executives and managers rush into, and “project out” a self-centred, dull and mechanical story in their own context expecting others to go “wow”. They don’t want to listen to solicited advice (ego) or see a need to invest in the requisite preparatory work.
When the reality is nine times out of ten they receive a polite “that is nice to hear, I’ll have my subordinates meet you”, “let us think about it” or “we’ll get back to you”.
What’s in it for the other party (compelling real and immediate business with minimal personal risk), and the scarcity (clearly cannot wait for other alternatives), is simply not evident.
Nor does the other party have the time, energy or money to investigate if it indeed exists.
95% of such meetings in my experience lead after the first or if you are lucky, a second meeting, to a “no need” or “no urgency” decision.
You and your story-telling (“positioning”) are the problem. If you think you are good at it but see a growing pattern of such responses, look yourself in the mirror, park the ego, and take qualified expert advice. You just might see the error of your ways.
If your ego or blind belief in your proposition won’t allow you to do so or you don’t see fault in your own language, the uncomfortable truth is no amount of wishful thinking, is going to generate your desired outcome.