We can all make wrong turns and I believe everyone deserves the benefit of doubt until such time that they demonstrably don’t warrant it (hard evidence, strong anecdotal information). Some of my best client relationships have taken unplanned detours and I have needed assertive efforts to get them, not as the The Beatles lyric goes, “back to where you once belonged” but to where our ideal future lies.
Here is what I have seen it takes, as entrepreneurs, to succeed:
Recognising and adapting to the other party’s comfort zone (levels of assertiveness and responsiveness).
Appealing to their self-interest (what’s in it for them).
Not taking their behaviour or comments personally (we’ve all walked into another meeting still hot under the collar from a conversation that didn’t go the way we visualised or hoped).
Confronting behaviour or points that you deem critical or highly important to achieving the immediate goals (relationship building, converting interest into business, implementing agreements or expanding relationships). Ignoring the rest.
Not being afraid to take and articulate a contrarian viewpoint.
Knowing where you want the conversation to lead to and re-directing it with appropriate questions back into the “swimming lane”.
Having in place definitive next steps (follow up in person, by phone or email, or exchange of information).
Sticking your courage to the wall. The perseverance and resilience to see your conversation gets back on track or the acceptance it is pointless pursuing it further, and moving on, irrespective of the “potential” rewards on offer.
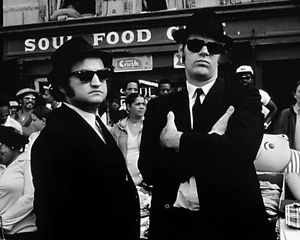
So you want to put your old team together, do a few gigs with past clients, get some bread? Bang! Five million bucks.
Here is the litmus test for those aspiring corporate executives and entrepreneurs seeking to “go again” in a new corporate or entrepreneurial venture, based on hundreds of situations I have been privy to:
Do those market needs that were fundamental to our past success exist today? Can we anticipate market needs for our expertise resulting from impending changes in technology, regulation, demographics, distribution, capital flows and so on? Can we create new market needs for our expertise that our clients have not thought about before?
Do we collectively possess superior capabilities to address those needs in today’s and tomorrow’s marketplace, not in a prior existence or environment? For example, in an electronic trading environment, a commodities or an insurance broker’s past competitive advantage – their interpersonal competencies (face-to-face negotiation) and “black book” of contacts – has been significantly eroded in this century. Equally, success in a large corporate setting is notoriously difficult to replicate in a small entrepreneurial business, irrespective of time (skills, behaviours, expertise).
Do we possess the requisite enthusiasm today, and in future, to undertake the work? In other words, are we ignoring the fact that our colleagues aren’t the same people they used to be 3 or 30 years ago. We are constantly changing, as is our interests, courage and risk tolerance.
Only in the movies to paraphrase Elwood, are you not going to get caught out if you cannot sincerely answer “Yes” to all of the above unless you believe you are on a mission from God!
Businesses don’t become insular, their leaders do. When leaders are so focused managing “in” their business that they overlook or are increasingly disinterested in the changes taking place around them (clients, markets, products, technology), they’ve made a deadly choice. Defending what they have is a bigger priority than embracing new ideas and new ways to evolve. No surprise then that the “inwards thinking” permeates down to middle managers, who see little or no incentive in promoting experimentation on the front line. Faced with more effective alternatives, clients walk, and the brightest employees walk. By the time, the “alarm bell” is sounded, all too often it is too late, particularly in small businesses.
When you blindly see technology as an “end” in of itself, not a “means” to a more impressive client experience, greater productivity, reduced risk and so on, you self-limit your own power and control. Think about that for a minute.
I have just finished a week of speaking to Thai and Swiss fintech and insurtech delegations here in London. There is a marvel at the high tech “community” that the UK and in particular, London, has created, built and exploited globally. I am talking about a digital community experience where people interact frequently, are drawn together by the quality of the people “present”, acts as peers, reciprocate and in so doing, help everyone live a more fulfilling life. Entrepreneurs, investors, venture builders, advisers, large corporates and governmental organisations in harmony. It is incredibly difficult to create community, as this week’s visitors readily pointed out. It requires a strong brand, impressive new intellectual property, fearless promotion and new ideas.
Those who bemoan the waning global appeal of the UK in a post-Brexit world, might want to take note of Britain’s singular success.
Why do we place more faith in ageing technology than in ageing people? The older and wiser individuals are, surely, the more productive they are in resolving problems or in raising performance levels? Equally, the inverse is true of ageing technology. Yet as a society, we are more trusting of computers than human knowledge (car mechanics), more tolerant of computer error than human error (air traffic control failures) and more aggressive in unilaterally retiring people than legacy systems (insurance companies).
If my 8yo daughter can quickly learn from defeat in the 200m final at her school sports day, why cannot adults do the same in a competitive business situation (a bid process, an investor pitch, a career opportunity)? We read too much into single events or circumstances (poor feedback). We allow them to unduly affect our mindset (bruised ego). We set unrealistic expectations in a highly ambiguous or complex environment (a professional gambler rarely generates more than 8-10% annual return in a great year). We refuse to take accountability (seek blame not cause). We surrender the power and control we possess to positively impact future events (we give up). If you recognise any of these today in your own behaviour, if you are a Parent, look at your child’s reaction and ask “what’s the lesson for me?”.
In a momentous week for sports betting and gaming companies in the United States and UK, there is a lesson for all of us. Quit whining about events largely out of our control that go against us (legislative changes) and maximise our investment in innovation and readiness for events that go for us.
Back in 2014, HSBC triumphantly announced a dedicated pool of $200 million to fund an innovation team and direct capital to young entrepreneurial fintech businesses. It has made some small bets in the intervening years and housed 3,000 digital techies in a separate London building because in the words of then CEO-Stuart Gulliver “we have a cultural issue.” Yet these actions masquerade a more profound Board and Senior Management issue: a fierce split has persisted for over 5 years about the priority that should be given to innovation, and the probable return on the time invested.
If innovation, internal or external, is truly critical to the business or profit centre’s future, why wouldn’t it sit within individual P&L’s, and the accountability reside with the appropriate P&L leader? When large organisations persist in setting up innovation labs, accelerators and dedicated corporate venture units too often they are “divorced” from the cut and thrust of the day-to-day business. They point to an unspoken truth, innovation isn’t really a strategic priority for certain powerful voices and/or the environment is insufficiently supportive of bold ideas or foreign bodies. Which is it? Common sense dictates that those leadership issues must be fixed first BEFORE investing a dime on innovation initiatives.
ICE Totally Gaming likes to style itself as “the only B2B gaming event that truly brings together the international online and offline gaming sectors”, here is some future thinking about the sector fresh from last week’s annual event.
The biggest event headline was a pointed article in The Guardian questioning the industry’s evolution in a #MeToo world (overt sexualisation of products). For a sector, whose branding has heavily relied on testosterone-fueled excitement, it is an awkward question with few, if any, obvious answers. When for example, over 50% of Las Vegas revenues arise from non-gaming tourism and events, “what happens in Vegas may no longer stay in Vegas” might need to be the new logo, at least in the corporate events market.
Caesar’s Entertainment, arguably the must public US corporate casualty in the 2007/8 financial crisis, is back on the front foot. After 10 difficult years, the Mark Frissora-led business has a spring in its’ step. The ex Hertz and GE executive is exuding confidence, exploring multiple partnerships and projects. Often in ways the Caesar’s brand has never successfully been positioned in adjacent markets internationally.
Italy remains a gaming paradox. Wrapped in regulation and taxation issues like many US markets, operators and investors can see ripe apples hanging on the trees but their attempts to grab them are constantly frustrated.
US sports betting and the US Supreme Court judgement. Everyone is gearing up to get in on the act, not least the US tribes, who with smaller, more entrepreneurial business models may be ideally-placed to bring the most innovative ideas.
UK sports betting is approaching a huge fork in the road, ahead of the Government’s ruling on fixed odds betting terminals or “pokies” to my Australian friends. Stick with limits of four machines per betting shop and a £100 stake per play, a ferocious political and media wind (Daily Mail front page hardship stories. Restrict stakes to £2 per play (prevalence of social welfare issues), see sports betting “majors” (Ladbrokes Coral, William Hill) and others dependent on their largesse (UK horse racing, UK government tax take) face a seismic change to their business models (30% reduction in gross gaming revenues, closures of 30-40% of their betting shops, 1000 of redundancies). Should we care? That depends on your view as to who is responsible for an individual’s actions. My personal opinion is that I am firmly against any form of gambling where there is not a fair and equitable chance of the punter winning long-term. If you applied my principle, we’d be closing down swathes of automated gaming machines, online card/roulette games and pools betting in casinos, bookies and so forth, where the “house” has a huge advantage (size of take out). We’d have more revenues directed to “equitable gaming and betting”.
2018 is arguably the most profound and volatile year for gaming and betting’s adaption to changing societal mores, regulation and tax. Yet for the smartest investors and regulators, this might well be the greatest year of opportunity (upturn in incumbents business models and branding, new markets, new value propositions, new ways to attract and retain customers, new ways to adapt to regulation and tax risks).