Posts Tagged ‘capital’

Serendipitous Dealflow

Thursday, July 11th, 2019

Mid-market businesses need three amortising and increasing pools of capital: cash, credit and investment, yet a great many I meet, don’t take sufficient care of their finances. They must forego one of their best acquisition-driven growth alternatives – unstructured business sales.

There is two distinctly different situations:

  1. Structured acquisitions, when a business is brought to your attention or you consciously go looking for it, and at the right time, you have sufficient capital and a compelling proposition for the seller (target acquisition or merger).
  2. Unstructured acquisitions, when a business is brought to your attention, the timing is unknown, your capital position may or may not be ideal, and yet you possess the means (liquidity) and volition to turn on your heels to create a compelling proposition for the seller (sale of a competitor, special situation, succession issue).

Do you go out to a late night social engagement with enough cash and credit cards in your pocket to choose the transport mode home, the time of your departure, and to “go with the mood” or must you always rely on finding a nearby ATM, scheduled public or private transport and be dictated to irrespective of the fun? Preparation and readiness trump planning!

Investor Due Diligence

Thursday, April 11th, 2019

How many alternative asset managers can you demonstrably say are well run businesses? I am talking about organisations that work smartly not hard, their employees have time to pursue their passions, and they reinvent themselves time and time again. The honest to god truth is that most of these small and mid-sized businesses would fail their own criteria of investable businesses when unmasked. That begs the question, if you are a superior entrepreneur why would you want to answer to a “new boss”, who is ill disciplined, disorganised and dysfunctional? To think that you can draw a distinction between their money and how they manage themselves, is naive at the extreme.

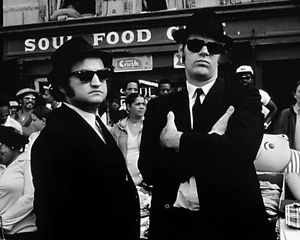
We’re Putting The Band Back Together

Friday, February 15th, 2019

So you want to put your old team together, do a few gigs with past clients, get some bread? Bang! Five million bucks.

Here is the litmus test for those aspiring corporate executives and entrepreneurs seeking to “go again” in a new corporate or entrepreneurial venture, based on hundreds of situations I have been privy to:

  1. Do those market needs that were fundamental to our past success exist today? Can we anticipate market needs for our expertise resulting from impending changes in technology, regulation, demographics, distribution, capital flows and so on? Can we create new market needs for our expertise that our clients have not thought about before?
  2. Do we collectively possess superior capabilities to address those needs in today’s and tomorrow’s marketplace, not in a prior existence or environment? For example, in an electronic trading environment, a commodities or an insurance broker’s past competitive advantage – their interpersonal competencies (face-to-face negotiation) and “black book” of contacts – has been significantly eroded in this century. Equally, success in a large corporate setting is notoriously difficult to replicate in a small entrepreneurial business, irrespective of time (skills, behaviours, expertise).
  3. Do we possess the requisite enthusiasm today, and in future, to undertake the work? In other words, are we ignoring the fact that our colleagues aren’t the same people they used to be 3 or 30 years ago. We are constantly changing, as is our interests, courage and risk tolerance.

Only in the movies to paraphrase Elwood, are you not going to get caught out if you cannot sincerely answer “Yes” to all of the above unless you believe you are on a mission from God!

UK’s Tech Gem

Friday, July 6th, 2018

I have just finished a week of speaking to Thai and Swiss fintech and insurtech delegations here in London. There is a marvel at the high tech “community” that the UK and in particular, London, has created, built and exploited globally. I am talking about a digital community experience where people interact frequently, are drawn together by the quality of the people “present”, acts as peers, reciprocate and in so doing, help everyone live a more fulfilling life. Entrepreneurs, investors, venture builders, advisers, large corporates and governmental organisations in harmony. It is incredibly difficult to create community, as this week’s visitors readily pointed out. It requires a strong brand, impressive new intellectual property, fearless promotion and new ideas.

Those who bemoan the waning global appeal of the UK in a post-Brexit world, might want to take note of Britain’s singular success.


© James Berkeley 2018. All Rights Reserved.


3 Deadly Sins First-Time Venture Capital Fund Managers Rarely Avoid

Wednesday, April 18th, 2018

Why do so many first-time venture capital fund managers, who have been a success in their past, cease to act like a success when raising their first fund? Undoubtedly, the fundraising journey is long, on average somewhere between 15 to 24 months for funds under $150 million from firing the gun until the final close. Nowhere is that harder for General Partners, who are new to the investment game and of limited interest to institutional money. Over the past 10 months, I have had first-hand experiences with 6 fund managers in US and Europe and talked to a multitude of placement agents, who have shared their experiences from over 120 such fundraises. Three deadly sins:

  1. General Partners underestimate the three pools of personal capital (cash, credit and investment) that they need to successfully arrive at their desired destination and thrive. They over invest in non-essentials (expensive office space, hiring employees), at the outset, and under invest in external expertise (fundraising, skills development) when they most need it, typically, in the tough grind that follows some immediate success  securing a cornerstone investor.
  2. General Partners underestimate the importance of maintaining a high level of self-worth. They allow a “poverty mindset” to quickly become their default position. They jump on the first offer of committed capital driven by a fear of failure, they beg for favours (introductions, expertise) on terms they’d never accept and they fail to act like a peer in front of investors (constantly “pitching” rather than investing appropriate time building a peer-level trusting relationship).
  3. General Partners underestimate the return on their time invested in accomplishing various activities along the “journey”. They spend excessive amounts of time “fine-tuning” their methodology at the expense of articulating the results and value the potential limited partner walks away with. They allow their intellectual curiosity and ego, to lead them into targeting investors, who are highly unlikely to commit, in their desired timeframe. Why? They consciously ignore who they are today (an ambitious first-time manager with an investment thesis yet to be proven, and zero successful exits) and they are overly pre-occupied with who they imagine themselves to be in future for ego reasons (the next Fred Wilson, Bill Gurley, Josh Kopelman).

The final thought: You might be a great investor but first, can you actually create and build a successful business (skills, behaviours, expertise)? I am not talking about a division of a large VC firm, a global bank, a management consulting firm or something you did on the side in university. I am talking about a boutique asset management business.  That is the first question your highest potential limited partners are trying to convince themselves about.

© James Berkeley 2018. All Rights Reserved.

Bring Something Meaningful

Wednesday, March 29th, 2017


I get approached at a minimum, by 3 people a week proposing some form of “collaboration”. Most commonly, other advisers, entrepreneurs, co-investors and bankers trying to access my investor or client communities and their capital, people or innovation. In most cases, they are decent people with a genuine request, who have been a success in their corporate careers. In their latest entrepreneurial incarnation, they have “capped” out their personal networks and/or they are unable to accomplish their goals without external assistance. Their “well” is running dry and they want me to share my water. They are largely offering symbolic (greater presence or a share of faux-success fees), not meaningful value (a powerful brand or actual cash).

I am a huge believer in collaboration as a powerful form of leverage. However, first, it needs to pass my litmus test:

  1. Combined, there is a scarcity and dramatically enhanced value that will significantly impact the speed and quality of my client acquisition prospects.
  2. There is an attractive short-term business opportunity of mutual interest (potential client, visible need with a strong fit and ease of implementation).
  3. I can and definitely want to help after considering prudent risk and potential reward.

I’d suggest I am not alone if you think about the quantum of conceptual collaborative discussions that you are presented with. Do you possess these simple questions, to reach a fast conclusion or do you allow multiple meetings and information exchanges to follow before reaching a conclusion?

Above all, is the other party bringing something meaningful? Yes or No.

Nothing more is required.

© James Berkeley 2017. All Rights Reserved.


What Is Your Story

Tuesday, May 31st, 2016


image


Every week I get smart, intelligent entrepreneurs coming to me for “help” with strategy and tactics to grow their business, raise capital, partner or even exit. I decline the overwhelming majority not because they don’t have a smart proposition but because I don’t have confidence that they can create and communicate a compelling story.

If they cannot convince me that they can get over the line, why would I invest my time and energy in convincing others? Of course, there are people I overlook who go on to prove me wrong.

The problem I find is that Founders, who may have been hugely successful in a big organisation or a different environment automatically assume their past performance and credibility confers a compelling story to others. Much as the celebrity dropping the “do you know who I am” line at the overbooked airline desk or the nightclub hostess. It rarely works.

It is about today’s story, today’s investment decision, and today’s health of your business.

Who are you today? What do you actually represent to a high potential investor, buyer or partner? How are they better off or personally better supported in investing in your success?

Knowing the answers to those questions doesn’t confer success but it sure gets your head and story into the appropriate context.

© James Berkeley 2016. All Rights Reserved.

The Perils of Hazy Horizons

Tuesday, March 8th, 2016

horizon


One of the senior politicians in the Brexit debate urged voters on British television last night to give serious thought to the type of country and life they want to have in 40 years time. Predicting what will happen in 3 years time, as anyone sitting in the executive office of a global bank in 2004 will attest to is fraught with huge inaccuracies and serious consequences! The pace of change has never been as dramatic (technology, capital, supply of talent, societal changes and so forth).

The art of management is to balance short and long-term profitable growth and make informed decisions about the health and well-being of the organisation. To effect change successfully and bring employees with them, mid-level managers in particular need to understand how they must adjust their own behaviours and actions in highly ambiguous situations.

To make serious predictions about the long-term and to put the risks and benefits and action in the appropriate context anything more than a 5-7 year horizon is really an intellectual not a commercial debate. Even in government funded infrastructure projects and macro inter-governmental policy initiatives (climate change, energy, healthcare, education and so forth). That is why I smile when I see organisations such as Lloyd’s of London’s (2026 Vision) and other global organisations expecting that their best laid plans will be taken seriously by their key constituents. It is a collection of predictions, which the forecasters will never be held accountable for and those asked to implement it struggle to grasp what it really means for them or their colleagues.  Fact.

Let’s get back to pragmatic outcomes, alternatives, assessment of benefits/risks, timing and action within the proposed investment parameters.

© James Berkeley 2016. All Rights Reserved.

An Investor’s View: Attracting Intelligent Capital to Innovative Ideas

Thursday, February 11th, 2016

I am thrilled to announce that I have been asked to be a contributor to VC-List, the pre-eminent online source for advice on turning innovative ideas into billion dollar businesses from people, who have invested in, led and advised real businesses. Here is a link to the first article “Getting Started in Raising Venture Capital” drawn from my war stories, experiences and insight with over 75 businesses in North America, Latin America, Europe and Asia that have successfully attracted funding from corporate venture capital, traditional VCs, HNW investors and so forth at various stages of their journey:

Getting Started in Raising Venture Capital


Bedtime Profitable Growth Lessons

Tuesday, September 22nd, 2015

When I read bedtime stories to my daughter, there are tales of witches flying on broomsticks, young children wandering into the forest alone dark at night and absentminded Fathers getting soaked trying to repair the garden hose. At certain points she might say “I am scared”. When I ask what she is scared of, she responds, “I am scared of what is going to happen to “X” on the next page”.

Likewise we accept challenges in profitably growing businesses, knowing that there are circumstances under our control (the quality of our management, employees and the level of uncertainty within the business) and there are others that are not (competitive threats). What we know is that if we are to develop we must increase our learning. We learn by applying our past (expertise and experience) to transform our clients’ future. Our future is a function of our resilience to events outside our control and continuing to be of value to our clients (reinvest the lessons learned in new, faster, more impressive approaches).

Lesson #1: The art of management is the ability to balance the demands of key constituents for short and long-term profitable growth.

Lesson #2: Not all constituents (shareholders, board, employees, business partners and so on) are equal. Not all demands are equal (EBITDA growth, higher pay, happier clients). Behind every demand is an emotional imperative (improved image, enhanced peer recognition, a promotion) and a logical objective (lower acquisition overheads, optimum size of business, attracting word class talent). Dig for both, orient your management approach around both.

Lesson #3: “Speed” (climbing to the next level) is as important as “quality” (existing revenue generation).

Lesson #4: Success arises in the implementation of a strategy (arriving at the desired future state), not the formulation. Credit may be given to the latter but the glory goes to those, who accomplish the former. Lee Kwan Y

Lesson #5: You start by determining what your vision is and what is “mission probable”. There are a great many visions that are possible in the conceptual world but missions that are improbable (capital, people, innovation, implementation) in the real world. There are a small number of visions that are possible in the conceptual world and mission that are probable in the real world. Don’t kid yourself because you can point to one exception, who got lucky!

Lesson #6: If you are not failing, you are not trying hard enough. It is always odds against (less than 50%) predicting the future. The best management teams are probably successful no better than 1:3 with new product innovations or international expansions. What you must believe is that when you have success, the rewards are sufficiently large to cover the losses plus the ongoing costs of profitably growing the business (payroll, pension, capex, new hires etc.).

Litmus Test: Is there someone I can point to (highly similar sector and recent scenario) who has visibly travelled the same profitable growth journey as I am seeking to pursue? Are there lessons I can apply to accelerate the speed towards our immediate profitable growth (reducing labour intensity)? Are these lessons I can apply to enhance the quality of our profitable growth (repeat business, unsolicited referrals) such that moving to the next and the levels beyond that is sustainable?

If you cannot point to a real world example, it may well be for a very good reason. The path you have chosen is improbable or the timing has never made sense previously.

Of course, there are environmental changes (technology, access to capital, demographic, social) that make the previously improbable, probable. That is where the “unicorns” (AirB&B, Xiaomi, Moneysupermarket.com) emerge from but they are the exception, not the rule.

© James Berkeley 2015. All Rights Reserved.